

Last month, I wrote about an industrywide litigation campaign — a coordinated series of federal lawsuits by Anthem/Elevance, UnitedHealthcare, and Blue Cross Blue Shield affiliates targeting the providers, hospitals, and billing companies that have used the No Surprises Act’s Independent Dispute Resolution process to seek appropriate payment for care already delivered. The lawsuits deployed nearly identical legal arguments — RICO violations, ERISA claims and fraud allegations. So far, that strategy doesn’t seem to be working for Big Insurance.
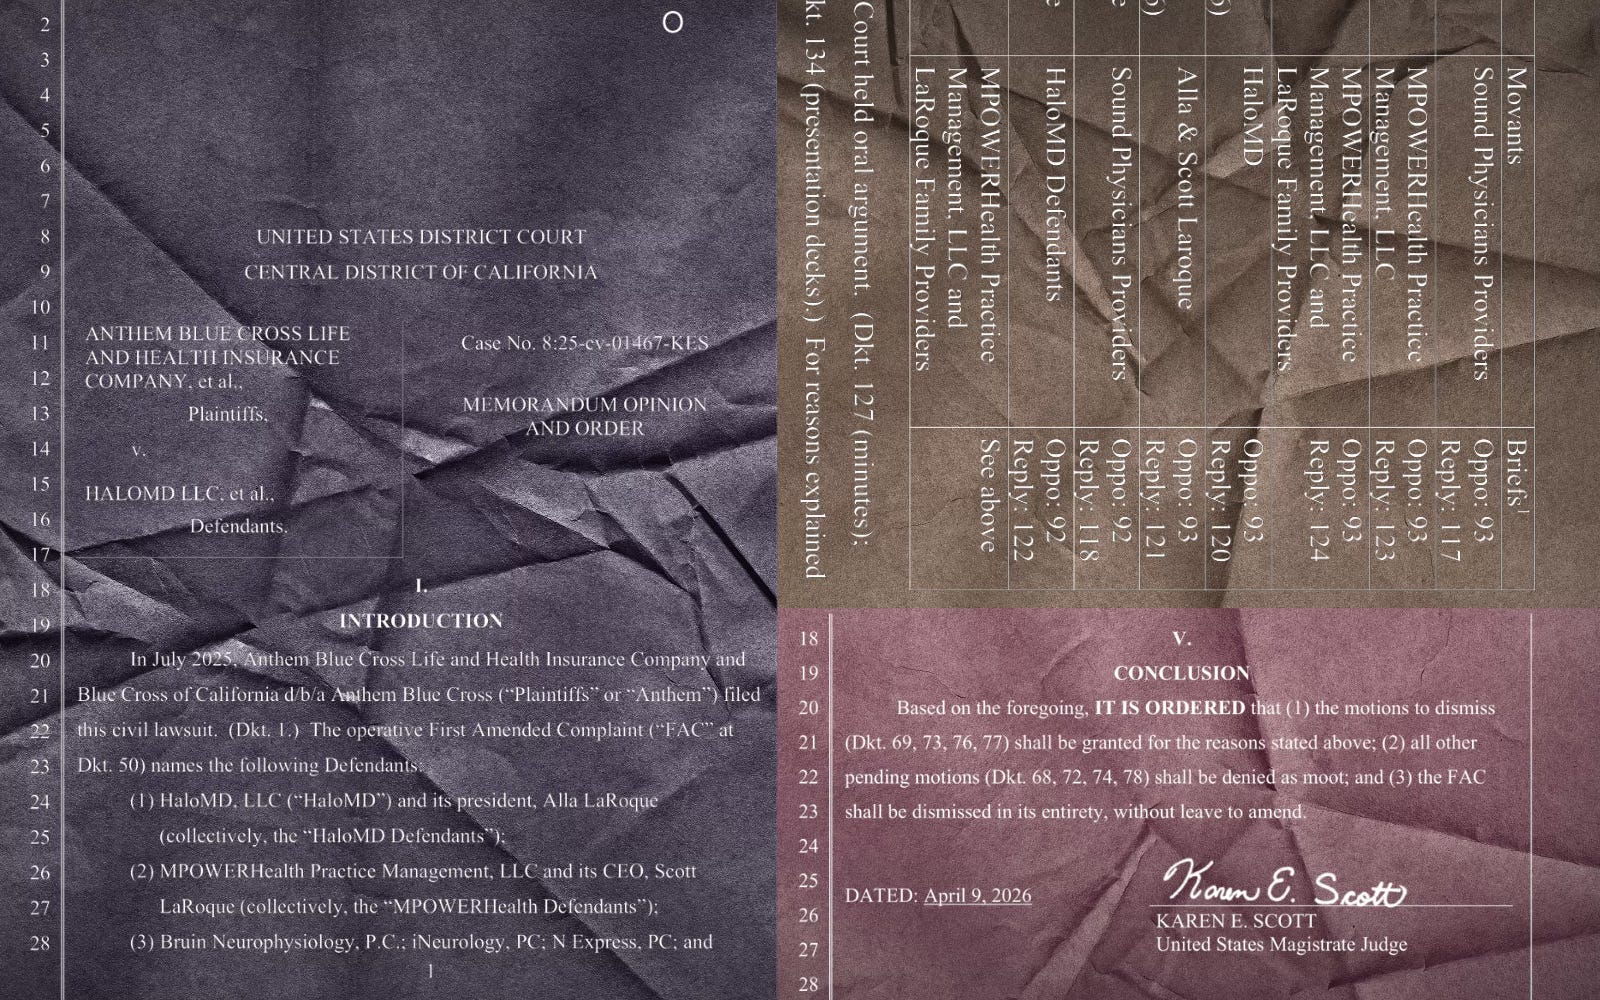
On April 9, Magistrate Judge Karen Scott of the U.S. District Court for the Central District of California dismissed the federal claims Anthem brought against HaloMD, a billing company, and its co-defendants.
Here’s a quick refresher of what this is all about.
Congress passed the No Surprises Act in 2020 to address a genuine patient nightmare: you go to an in-network hospital but later get a bill for thousands of dollars from a doctor who treated you there but, to your surprise, was not in your insurer’s physician network. The law eliminated most of those surprise bills and established an Independent Dispute Resolution process — essentially arbitration — to settle payment disputes between insurers and out-of-network providers.
The IDR process was designed to be the endpoint: Insurers and providers submit their best offers and a neutral arbitrator decides what a fair payment should be.
As it turns out, insurers have been losing many of the arbitrations. Rather than accept that outcome, Anthem went to federal court and argued that HaloMD, which helps providers navigate the IDR process, was gaming the system — specifically, by submitting thousands of disputes Anthem claimed were ineligible and labeling them as eligible, and by deliberately flooding the system with more disputes than Anthem could respond to. Anthem also argued that arbitrators themselves were financially compromised, since they only get paid when a dispute is found eligible — creating, in Anthem’s telling, an incentive to rubber-stamp ineligible claims.
Judge Scott was not persuaded. In her ruling, she found that the No Surprises Act allows courts to review arbitration decisions only under very narrow circumstances — corruption, fraud, or misconduct that could not have been discovered during the arbitration itself, such as bribery, undisclosed bias, or willfully destroyed evidence. Anthem, the judge said, had not met that bar.
She also noted that Anthem’s own complaint revealed the flaw in its argument: the IDR process already allows participants to flag disputes they believe are ineligible directly to the arbitrator. The remedy Anthem claimed it needed federal courts for already existed within the system Congress built. As Judge Scott wrote, if courts adopted Anthem’s position, “nearly every eligibility determination disputed by an [independent dispute resolution] participant would be subject to review in federal court” — which would gut the entire streamlined process the statute created.
On the arbitrator incentive argument, the judge was equally direct. The fee structure Anthem complained about was established by Congress. That, she wrote, is “not akin to bad faith or bribery.”
The state law claims were dismissed without prejudice, meaning Anthem could attempt to refile them in California state court. But the federal claims — the heart of the case — are gone.
In a statement after the ruling, Anthem called the decision “procedural”, said it “did not address most of the company’s arguments” and that it would appeal Judge Scott’s ruling.
To be sure, the California ruling doesn’t end the industry’s litigation campaign. Three parallel suits brought by Blue Cross Blue Shield affiliates — in Texas, Georgia, and Ohio — remain active. Similar cases from UnitedHealthcare continue in other jurisdictions. And Anthem’s announced appeal means this California case will now head to the Ninth Circuit, where the stakes will be higher and the precedential implications broader.
There’s also a separate front worth watching: a case before the Fifth Circuit involving the Texas Medical Association that could reshape how the qualifying payment amount — the benchmark insurers use in IDR — is calculated. A ruling in that case won’t just affect arbitration; it could directly raise patient out-of-pocket costs for out-of-network care.
One thing Judge Scott’s ruling accomplish is this: it establishes that federal courts are not the appropriate venue for insurers to relitigate arbitration outcomes they don’t like. Judge Scott’s reasoning — that the IDR process contains its own mechanisms for raising eligibility disputes, and that Congress deliberately limited judicial review — is now part of the legal landscape that other courts will have to contend with.
Shame on these insurance company litigants
The piece most plan sponsors miss in this litigation pattern: when a fully insured plan loses an IDR arbitration, the insurer pays the award. When a self-funded plan loses, the employer does. Anthem is pursuing ERISA theories in federal court nominally on behalf of plans whose sponsors often do not know the strategy exists, let alone whether it is being pursued in their interest.
The Fifth Circuit QPA case deserves the same employer lens. If the calculation has been systematically depressed, self-funded plans have been underpaying out-of-network claims for years, and the correction will land on plan reserves. The carrier does not carry that risk. The plan sponsor does.
Grateful for the coverage.